If you live outside the US, chances are your American address is either a virtual mailbox or a spot at a friend’s or relative’s home. Whichever it is, every envelope that arrives there carries a cost, whether financial in nature or otherwise.
With a virtual mailbox, many plans limit the number of items or scans you can receive each month, and junk mail quickly uses up that allowance. With a friend or family member, it is their doorstep and their recycling bin. Asking them to deal with a weekly stack of “You’re pre-approved!” letters addressed to you is a favor that wears thin fast.
The flood tends to begin once you start building US credit. Balance transfer offers from credit card companies, insurance quotes, and endless “pre-approved” card invitations show up again and again.
Below is why this happens and how to shut off most of it.
Why the Offers Keep Coming
Under the Fair Credit Reporting Act (FCRA), the credit bureaus are allowed to sell lists of consumers to banks and insurers. A card issuer decides what kind of customer it wants, for example people within a certain score range. The bureau then pulls every file that fits, and the issuer mails each of those people an offer. These are known as “prescreened” or “firm” offers.
Because this is a soft inquiry, your score is not affected. The sheer volume, though, is enormous: in April 2025 alone, over 285 million credit card mailers were sent across the US.
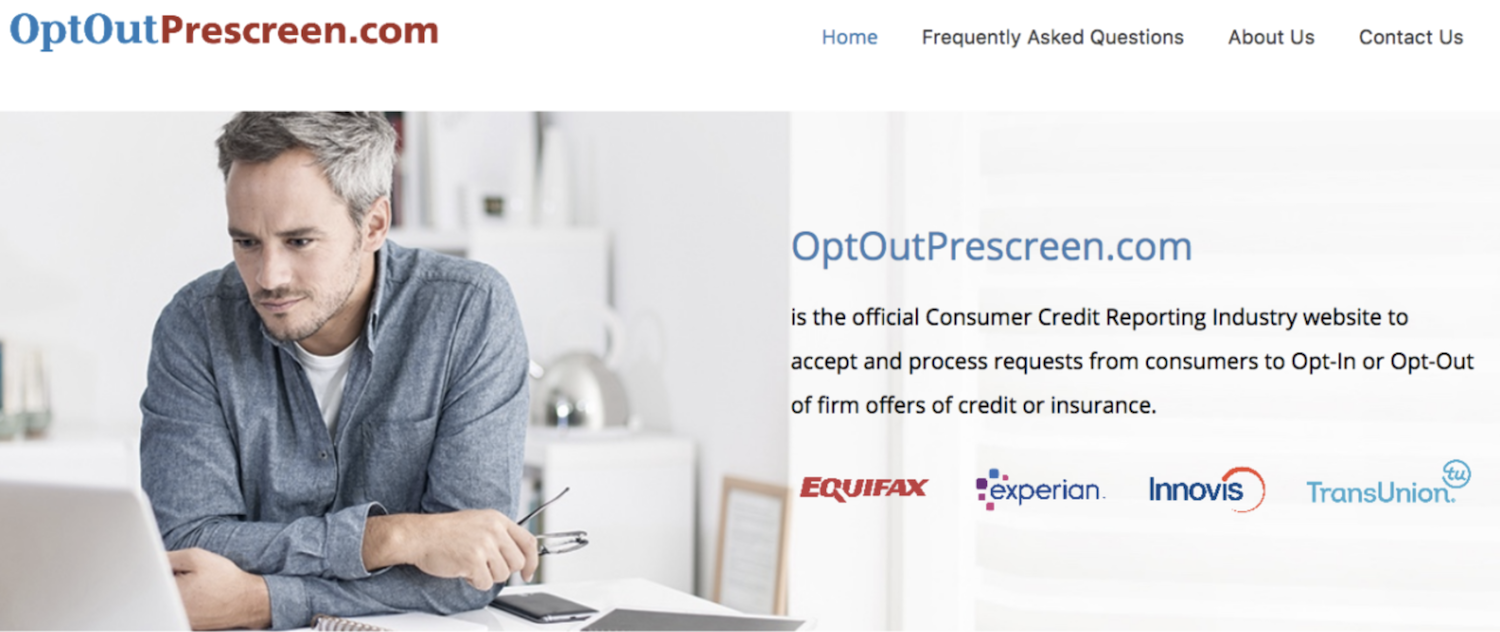
The same law also gives you the right to say no. The bureaus maintain a single official site for this, OptOutPrescreen.com, run jointly by Equifax, Experian, TransUnion and Innovis. One request covers all four.
OptOutPrescreen.com: Opt Out for Five Years Online
- Use a US VPN or proxy. The site will usually refuse to load from outside the United States.
- Open optoutprescreen.com and select “Click Here to Opt-In or Opt-Out,” which sits near the bottom of the page.
- Pick “Electronic Opt-Out for Five Years.” It is the only choice you can finish entirely online.
- Fill in your information:
- First and last name
- The US mailing address on your credit report
- ITIN or SSN
- Date of birth
- Submit the form, pass the security check, and take a screenshot of the confirmation page for your records.
The form accepts an ITIN in place of an SSN. The ITIN and date of birth are technically optional fields, but you should complete them anyway. To opt you out, the bureaus first have to locate your credit file, and those two details are what they use to match it. Enter your name and address exactly as they appear on your credit report.
Processing takes up to five days. Expect a few more weeks before the mail really tapers off, since offers that were already printed are still in transit.
What the Opt-out Does and Doesn’t Do
- It costs nothing. The genuine site never requests a card number or any payment. Type the web address yourself rather than following links, so you don’t end up on an imitation site.
- Your credit is unaffected. Opting out does not change your score or limit your ability to apply for cards.
- A permanent option exists, but it requires printing, signing and mailing a paper form. For most people living abroad, the five-year online route is the realistic choice.
- You can reverse it whenever you like, either on the same website or by phoning 1-888-567-8688.
- It covers only prescreened bureau-list offers. Statements from your own banks, catalogs, “Current Resident” flyers, and offers built from other data sources will still arrive.
- It applies to one person at a time. If others at the same address are also buried in offers, each of them has to file their own request.
DMAchoice.org: Cut Even More Junkmail
DMAchoice.org is the advertising industry’s do-not-mail registry. It charges $8 online, remains in effect for 10 years, and is meant to reduce promotional mail from companies you have no relationship with by roughly 80%. It does not handle prescreened credit offers; that is the job of OptOutPrescreen.
Together, the two services cover most of the junk.
Should You Opt Out While Building Credit?
Some card offers are available only through prescreened mailings, so if you want to see what issuers are sending you, you could wait. Most people in our community, however, choose cards based on research rather than mailers. And you can always opt back in later.
The whole process takes about two minutes, and your mailbox (or your aunt) will be grateful.
Have other tips for keeping junk mail away from your US address? Share them in the comments.